A Senate-only congressional disclosure week is when new periodic transaction lines appear on Senate eFD while your House filing-date window stays quiet—not a broken feed, and not proof that representatives stopped filing. Senate batches often arrive in clumps with longer trade-to-filing lag than many House PTRs, and they mix corporate bonds, funds, and equity lines where the ticker field is blank. ProBors lets you filter by chamber, sort by filing date, and open the source document before you write a story. This seven-step workflow is for those Senate-heavy weeks when row count is moderate but timing and asset type need extra care. This is research context, not investment advice.
Why Senate-only weeks confuse researchers
Congressional tables sorted by filing date can show a burst of Senate rows while House PTRs pause for several days. Three mistakes follow:
- Assuming House silence means “Congress is quiet.” Representatives file on a different cadence; a Senate dump in early October can dominate the feed while House activity resumes later in the month.
- Treating the filing date as the trade date. Senate periodic reports may cover September trade dates filed in October—headlines that say “Senator sold Visa this week” often mean “disclosed this week.”
- Ignoring no-ticker bond and fund lines. When
tickeris missing, the real story may be fixed income or a fund name buried in the description—not a mega-cap equity pick.
Senate-only weeks are a lag and asset-type problem first and a ticker narrative second. Pair this pass with the Senate stock trading tracker for periodic-report mechanics and with how to research House-only weeks so you do not compare chambers apples-to-oranges.
Seven-step workflow on ProBors
-
Define the filing-date window in writing. Pick seven calendar days (or align with your weekly review). You are measuring what became public in that window, not when trades occurred. Note the window at the top of your memo.
-
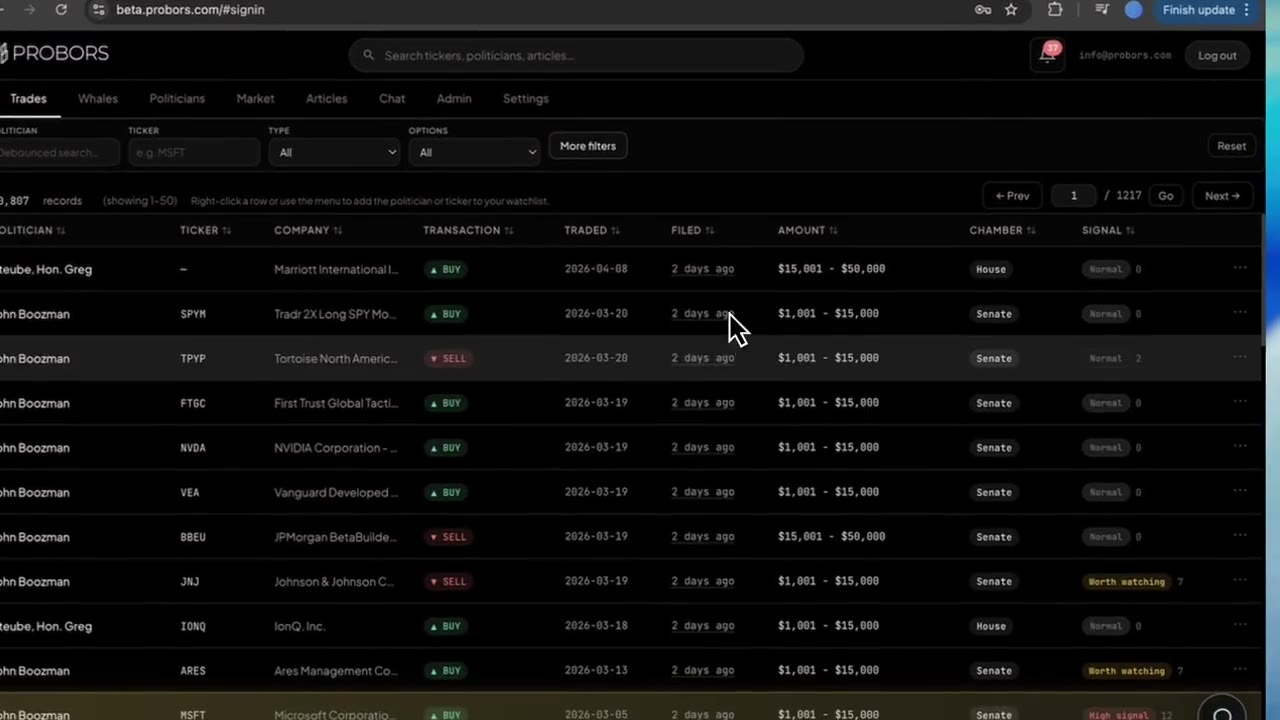
Run a Senate-first pass with the chamber filter. Sign in at probors.com, open Trades, sort by filing date descending, and restrict to Senate rows. Count distinct members who filed at least one line. If House rows are absent in the same window, label the week “Senate-only” so you do not benchmark it against a mixed batch.
-
Confirm House absence explicitly. Switch the chamber filter to House with the same filing dates. Zero House rows in-window is common during Senate clumps; write “no House PTRs in window” instead of assuming ingest failure. When House rows return, split them into a separate memo section.
-
Bucket by asset type before signal labels. Separate liquid equity tickers, blank-ticker bonds and notes, and fund or trust descriptions. Route non-equity lines to non-equity congressional research. Large multi-line Senate filings belong in large batch triage even when the rest of the week looks thin.
-
Log filing lag in whole days for every shortlist row. For each line, record transaction date, filing date, and lag (“21-day lag,” “27-day lag”). Senate-only weeks often contain September trades filed in October—use filing lag screening so timely-sounding headlines are not built on stale trade dates.
-
Verify in the original eFD PDF. From row detail, use Open original disclosure when present (see the original filing links guide). Confirm owner, asset description, and amended markers. One filing date with ten bond lines is one event, not ten independent stock picks.
-
Close with proportionality. Ask whether this Senate batch changes a watchlist entry. If not, archive the memo and wait for the next chamber mix. If yes, add one politician or one verified ticker—not every small-bracket line. Fold the outcome into your weekly disclosure review.
Examples from an early-October Senate window
Recent filings in ProBors as of November 1, 2026 show a Senate-heavy slice: equity sales filed October 1, 2026 with September trade dates near 27-day lag, and corporate-bond purchases filed October 7, 2026 with 21-day lag and no equity ticker.
| Politician | Chamber | Ticker / asset | Type | Traded | Filed | Lag | Amount range | Signal |
|---|---|---|---|---|---|---|---|---|
| Sheldon Whitehouse | Senate | V | Sale | September 4, 2026 | October 1, 2026 | 27 | $1,001 - $15,000 | Normal |
| Sheldon Whitehouse | Senate | JPM | Sale | September 4, 2026 | October 1, 2026 | 27 | $15,001 - $50,000 | Normal |
| John Fetterman | Senate | Corporate bond (no equity ticker) | Purchase | September 16, 2026 | October 7, 2026 | 21 | $1,001 - $15,000 | Normal |
Whitehouse’s Visa and JPM sales share a trade date and filing date—read them as one disclosure event, not two unrelated “Senate sold banks and cards” themes. Fetterman’s line is fixed income without a liquid ticker; do not map it to a single equity symbol without reading the eFD text.
What this does not prove
A Senate-only week does not show that the House stopped trading, that members coordinated, or that bond purchases predict equity moves. It only shows which chamber filed in your filing-date window. Long lag means public attention arrives after the trade window—not that the market “just learned” on the filing date. Signal labels rank attention inside a row; they are not forecasts.
FAQ
Does Senate-only mean ProBors is missing House data?
Not necessarily. Check probors.com/status if both chambers look empty. When Senate rows update but House does not, you may be between House PTR drops—note the window and keep the House filter ready.
How is this different from investigating stale Senate batches?
Stale Senate batch triage focuses on very old trade dates inside a new filing. This workflow focuses on chamber mix for a calendar week—you can use both on the same rows.
Should I compare Senate-only weeks to House-only weeks?
Compare process, not row counts. House-only weeks often emphasize trust labels and same-week PTR timing; Senate-only weeks emphasize batch lag and bond-heavy lines. Keep separate memo sections.
When should I trace a politician’s full history?
When one member files many lines on one date—especially blank-ticker purchases—open politician disclosure history before you infer a new theme.
Can I rely on signal scores during Senate-only weeks?
Use scores to sort attention, then verify in the PDF. High-bracket bond lines can carry “worth watching” labels without implying an equity thesis—read reasons in row detail alongside trade signal scores.
Research Senate disclosure batches with structure
Filter Senate periodic filings by date, log trade-to-file lag, and verify eFD PDFs on ProBors.
Get startedRelated reading
- How to research a House-only congressional disclosure week — the mirror workflow when House PTRs dominate
- Senate stock trading tracker — periodic reports, deadlines, and reading Senate rows
- How to investigate stale Senate disclosure batches — when trade dates lag filings by weeks or months
- How to screen congressional trades by filing lag — lag buckets for timely vs stale rows
- How to verify congressional trade disclosures before sharing — pre-publish checklist
Sources
- Senate Select Committee on Ethics — eFD search
- House Clerk financial disclosure
- STOCK Act — Pub. L. 112-105
- Senate Ethics — financial disclosure overview
- Rows were checked in ProBors and should be verified against the original filing.
- Ingestion health: probors.com/status
Sources & methodology
Last updated:
ProBors uses public disclosure records, SEC filings, House and Senate financial disclosure portals, market data, and in-product workflow checks. Articles are written as research education, not investment advice.